Equity & Life Transitions
Renovation ROI: Which Home Upgrades Build Real Equity Before Selling?
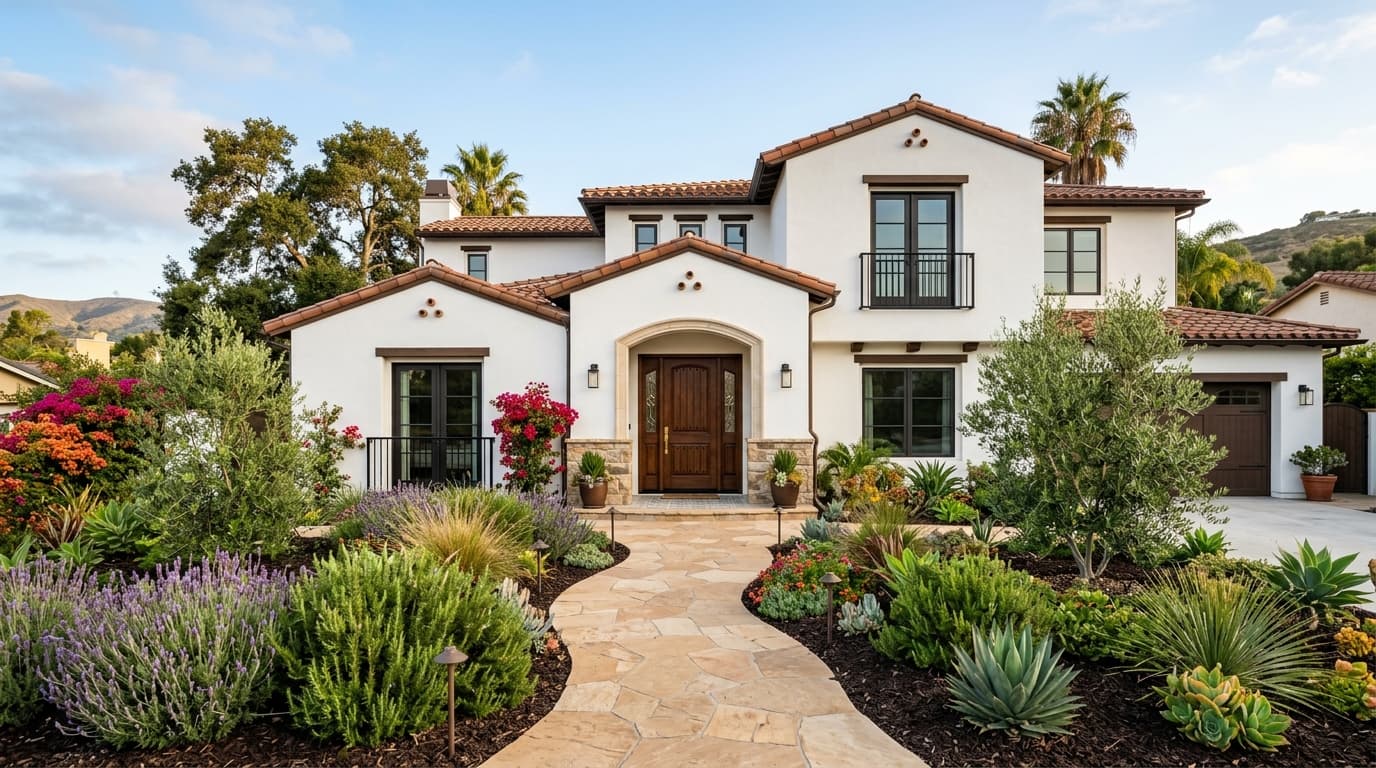
Which high ROI home renovation projects tend to make sense before selling, and how financing choices change the math.
Not every dollar you spend on a home comes back at sale. Some upgrades protect your value, some add real appeal and some mostly satisfy your own taste. If you are weighing high ROI home renovation projects before selling, a structured approach beats a wish list. Here is how to think like an investor about your own house.
Define ROI the right way
Return on a renovation is the change in what a buyer would pay, compared with what you spent, plus any financing cost. It is not guaranteed and it varies by market, price tier and quality of work. Published cost-versus-value studies can be a rough guide, but treat their percentages as general trends, not promises for your property.
A quick formula:
(Added value minus total cost) divided by total cost
A hypothetical: you spend $30,000 and a local appraiser or agent estimates it supports $24,000 of added value. That is a negative return of 20% in resale terms, even if you enjoy it. If you plan to stay for years, the enjoyment counts too. If you are selling soon, it should be weighed carefully.
Which high ROI home renovation projects punch above their weight
Based on general market experience, these categories tend to be worth pricing out first:
- Deferred maintenance: roof, HVAC, plumbing and electrical issues that buyers will otherwise discount heavily.
- Fresh paint and flooring: relatively low cost, broad appeal.
- Curb appeal: landscaping, entry door, exterior lighting.
- Kitchen and bath refreshes: cabinet refacing, new hardware and fixtures, rather than a full gut remodel.
- Energy efficiency: better windows or insulation may appeal, and some improvements may qualify for incentives; verify current rules.
Projects that often disappoint
- Highly personalized finishes
- Over-improving compared with neighboring homes
- Large additions without verified permits
- Luxury upgrades in a modest price tier
A helpful rule: do not renovate beyond what comparable sales in your area support.
Ask for local evidence
- Have a licensed agent walk through and tell you what buyers in your price band expect.
- Look at recently sold homes with and without the upgrade.
- Get at least two written bids from licensed, insured contractors.
- Confirm permit needs with your city or county.
How to pay for it
Options include savings, a home equity line, a cash-out refinance, or a renovation loan. A cash-out refinance replaces your whole mortgage, so compare the new rate with what you have now. An illustrative case:
- Current balance $400,000 at 4.0%: about $1,910/mo P&I
- Cash-out to $450,000 at 6.5%: about $2,844/mo P&I
That is roughly $934 more per month for $50,000 of cash, because the new rate applies to the full balance. In many cases a separate, smaller loan may cost less than refinancing everything, but the answer depends on your numbers. Borrowing only makes sense if the work has a realistic path to paying for itself.
Timing matters
If you plan to sell within a year, finishing a limited, high-impact list may be better than a long project that delays listing. Build in time for permits, contractor availability and surprises. Add a 10% to 20% contingency to any budget.
Keep records
Save receipts, permits and before-and-after photos. Documentation supports your pricing story at sale and helps with tax basis questions, which you should review with a tax professional.
Bottom line
The best high ROI home renovation projects fix what buyers worry about, polish what they see first and avoid overbuilding. Price each one against local evidence, then decide.
Your Next Step
I can help you model cash-out refinance trade-offs against potential equity gains using the Scenario Planner at /tools. Run a few versions, then call me at 714-204-8331 to talk through the one that fits your plans.
Illustrative examples only; not a loan offer or financial advice. Rates, programs and eligibility change, so confirm current details.
- high ROI home renovation projects
- renovation ROI
- home equity
- cash-out refinance
- selling a home
A better starting point
Have a question about your own situation?
Model Cash-Out Trade-OffsDan The Truong, NMLS ID 2115125. Information is for educational purposes only and is not a commitment to lend or an offer to extend credit. Loan approval, rates, and terms depend on credit, income, property, and underwriting, and may change without notice.